

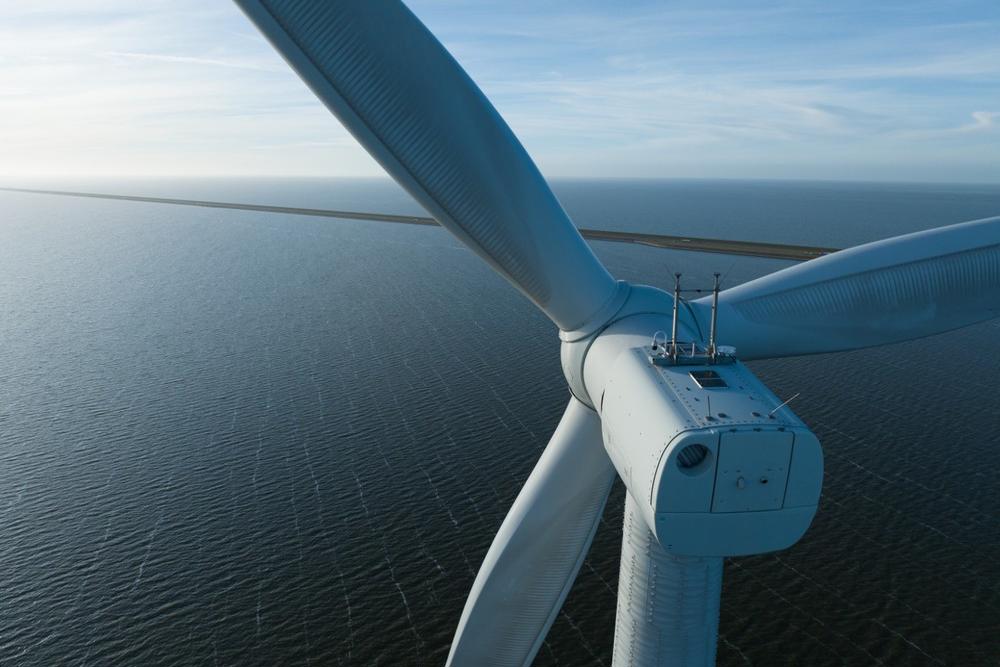
Europe’s offshore wind industry is shifting from setting ambitious targets to actually delivering on them, according to a new report from GlobalData.
Governments across the continent are redesigning auctions, clarifying revenue stabilisation tools, and speeding up permitting rules to lock in multi-gigawatt project pipelines.
The findings come from GlobalData’s Europe Renewable Energy Policy Handbook 2026, which frames offshore wind as infrastructure rather than just another source of power generation.
The report argues that offshore wind has become one of the few renewable technologies capable of delivering very large annual increments of low-carbon electricity at utility scale.
Attaurrahman Ojindaram Saibasan, Power Analyst at GlobalData, said price is no longer the only factor governments weigh when awarding projects.
“The key differentiator is no longer only who offers the lowest price, but who can deliver at scale under permitting limits, supply chain constraints, and increasingly complex grid integration,” Saibasan said.
One of the clearest trends identified in the report is the move toward two-way Contracts for Difference or similar tools designed to reduce revenue volatility for developers while preserving price discipline.
Policymakers are also introducing clearer rules around indexation, delivery timelines, and penalties for projects that fail to perform, along with new industrial and sustainability requirements.
Recent auction outcomes across Europe highlight both the risks and the momentum.
In Germany, a 2025 tender for two North Sea sites totalling 2.5 gigawatts drew no bids at all, a result analysts tied to the lack of revenue stabilisation mechanisms, unresolved permitting risk, and grid readiness that failed to line up with project timelines.
Other markets have fared better. France launched a combined tender of roughly 10 gigawatts in mid 2026, split evenly between fixed bottom and floating offshore wind across its coastlines, a sign of the country’s growing commitment to floating technology.
In the United Kingdom, the latest Contracts for Difference round awarded more than 8 gigawatts of fixed bottom offshore wind alongside floating projects, with fixed bottom strike prices coming in notably lower than in previous rounds.
Floating offshore wind is emerging as a particular focus for policymakers as fixed bottom technology remains limited to shallower waters.
Several governments are preparing dedicated floating tenders and adjusting subsidy structures to account for the technology’s higher costs and greater risk, aiming to unlock deep water wind resources that were previously out of reach.
The report also points to a broader shift in how offshore wind fits into national energy planning.
Rather than treating it purely as a source of electricity, governments are increasingly viewing offshore wind as a platform for industrial electrification, clean hydrogen and e fuel production, and stronger cross-border power interconnection.
Saibasan said the stakes extend well beyond emissions targets.
“The next winners will be those jurisdictions that combine credible auction design with fast, transparent permitting and investable grid delivery,” said Saibasan.
With multiple large-scale tenders already underway in 2026, GlobalData’s report suggests the coming years will determine which European countries succeed in translating offshore wind ambition into built, operating capacity.